Problem Validation Scorecard: Pain, Frequency, and Budget
A problem validation scorecard is a one-page worksheet, filled in once per account, that captures how often the problem happens, the yearly cost of the current workaround against your price, and a budget owner's completed commitment. Founders selling to business buyers use it before building, rating each block by its evidence so a frequent inconvenience cannot pass as a paid problem. The main constraint is a small sample: it supports a next decision, not a demand estimate.
What this worksheet helps you decide
This template is for founders at the idea-to-validation stage who have one problem in mind and need a sheet to fill in during customer conversations. It answers one question per account: is this problem a frequent inconvenience or a paid problem? Pain on this sheet means cost, meaning what the problem takes out of the business. How upset someone sounds is a note, not a rating. To choose between several candidate problems, use Is Your Startup Solving a Problem People Will Pay to Fix? For the order of work across a dozen accounts, use How to Test a Customer Problem Before Building a Product. This page gives the sheet itself, field by field, ready to copy.
The scorecard has three blocks: frequency, cost of the current workaround and budget commitment. Fill in one copy per account. Write the first four header fields once, before the first conversation, and keep them the same on every copy:
- Problem statement. In one sentence: who has the problem, in what situation and what it costs when it happens.
- Segment. One kind of account, narrow enough that the answers can be compared.
- Intended yearly price. A rough figure is enough, because the cost block compares against it.
- Required margin. How far above the price the yearly cost has to be, set before any answers come in.
- Account and contact. The company, the person answering and whether that person controls the budget. This one changes on each copy.
The U.S. Small Business Administration's market research guide says direct research can be time consuming and expensive, and it lists in-depth interviews among the direct methods. A one-page sheet keeps that spend on the fields that change the decision.
Every entry carries one of the four evidence tags from the Customer Interview Notes Template for Founders: said, seen, done or assumed. When nobody can answer a field, mark it unknown instead of guessing. Each block then gets one rating: Strong, Partial or Missing.
Fields for problem frequency
Frequency says how often the cost repeats. It is a multiplier for the next block and carries little weight on its own.
| Field | What to enter | Strong evidence |
|---|---|---|
| Last occurrence | The date, and what happened next | A date in a record you have looked at |
| Count in a period | How many times in a named period, such as the last full quarter | A count from a log, ticket queue, dispatch sheet or calendar |
| Pattern | Whether it clusters in a season or around a recurring event | Dates in the same record |
| Yearly count | The count scaled to a year, with the scaling written down | A full year of records; otherwise tag the scaling assumed |
- Strong. The count is seen or done, and it repeats often enough to matter at the cost in the next block.
- Partial. The account can date the last occurrence, but the count comes from memory.
- Missing. Nobody can date a last occurrence.
Fields for cost of the current workaround
Every account that has the problem already does something about it, even if that means tolerating it. The SBA guide frames the question as 'What do potential customers pay for these alternatives?' Answer it by costing one occurrence and then multiplying.
| Field | What to enter | Strong evidence |
|---|---|---|
| Current workaround | What the account does today, in one line | Watched in action or shown in a record |
| Money out per occurrence | Fees, refunds, credits, parts, fuel | An invoice or credit note |
| Paid hours per occurrence | Hours that would actually be cut or reassigned, times the hourly rate | A payroll line or timesheet |
| Revenue lost per occurrence | Sales or fees lost, as an average | Cancelled orders or skipped invoices |
| Hours that do not count | Time from someone on shift regardless, on its own line and left out of the total | The account confirms the time would not be cut |
| Cost per occurrence | Money out, paid hours and revenue lost, added together | The largest item checked against a record |
| Yearly cost | Cost per occurrence times the yearly count, next to the required margin | The budget owner has seen the figure and confirmed or corrected it |
| Who carries the cost | The person whose budget it lands on | That person names the cost |
For the hourly rate, use the account's own figure. A wage alone understates what an hour costs the employer. The Bureau of Labor Statistics Employer Costs for Employee Compensation release reported that total employer compensation costs for private industry workers averaged $46.89 per hour worked in June 2026, with wages and salaries averaging $32.82. That is a national average across occupations, so tag any figure built on it as assumed.
- Strong. The yearly cost clears the price by the required margin, and its largest item is seen.
- Partial. It clears the margin only on said or assumed entries.
- Missing. It falls below the price, or most of it is hours that do not count. An account in this position saves money by keeping its workaround, however annoying that is.
Fields for budget commitment
This block replaces stated interest with a step that costs the buyer something. Ask only after the cost block is filled in, so the request has a price to stand on.
| Field | What to enter | Strong evidence |
|---|---|---|
| Budget owner | The name and role of the person who can approve the spend | Confirmed by that person |
| Step requested | A deposit, a paid pilot, a signed order with a start date, or dated time with the approver plus access to records | The request as it was actually made |
| What it costs the buyer | The money or scarce time given up | A payment, signature or held meeting |
| Date asked and date due | Both dates, set when the request is made | A dated message |
| Date completed | Filled in only when the step has happened | Tagged done |
| Response if not completed | The refusal, silence or delay, in the buyer's words | A quote, tagged said |
Daniel's go-to-market mentoring page describes this step in its session list: 'Define a pilot outcome, a buyer commitment and the decision that follows the pilot.' That is his own description of his method.
- Strong. The budget owner completes a paid or dated step by the date.
- Partial. Someone without the budget acts, or a dated meeting is set but not yet held.
- Missing. Praise, a demo request, a free trial or a promise to pass it on.
How to read one completed copy
Read the three ratings as a pattern. Adding them up would let a strong count make up for a missing cost.
| Frequency | Cost | Budget | Reading |
|---|---|---|---|
| Strong or Partial | Missing | Missing | Frequent inconvenience. Drop it as a product, or keep it as a feature of something else. |
| Strong | Strong | Partial or Missing | The cost exists but nothing has moved. Check the buyer, the offer and the timing. |
| Strong | Strong | Strong | Looks paid for this account. Compare it with the other copies. |
| Strong or Partial | Partial | Any | Unsettled. Find the record that would move the entries from said to seen. |
| Missing | Any | Any | Undocumented. Ask for a tally over a named period, or stop with this account. |
If a copy fits no row, such as a budget owner who pays despite a low cost, ask that buyer what the cost block missed before reading anything into it.
A hypothetical filled example covering willingness to commit money or time
The following is a hypothetical example with invented details. It illustrates the worksheet and does not describe a real company, customer or measured result.
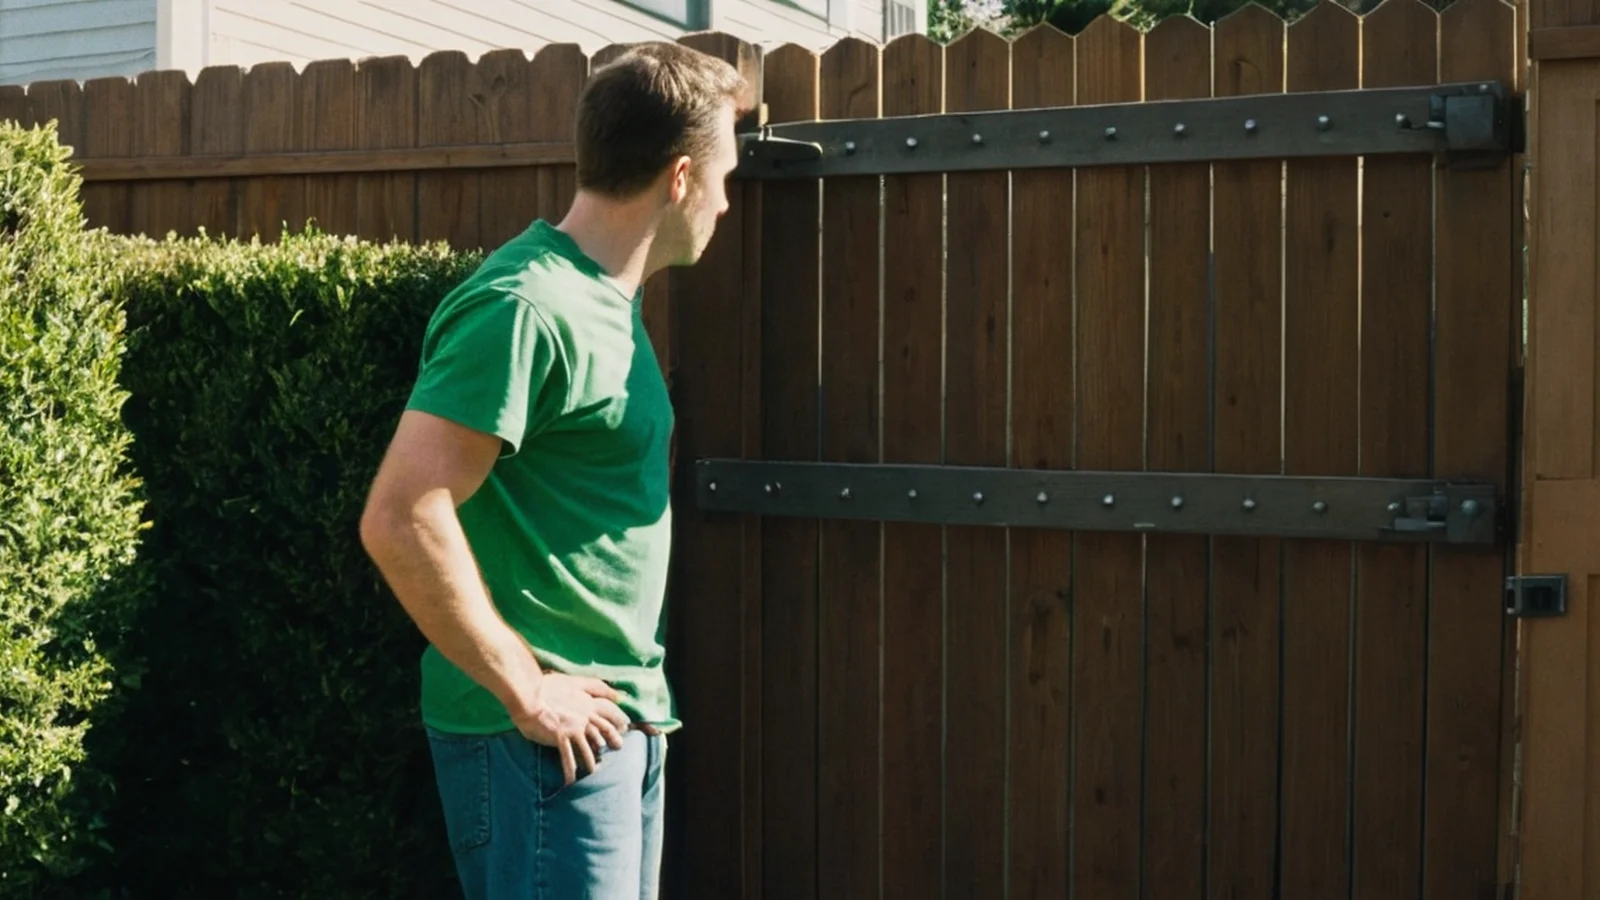
A founder plans a visit-day reminder and gate check for owner-run lawn care companies at an intended price of $89 a month, or $1,068 a year, with a required margin of twice the price, or $2,136. The problem statement: a crew reaches a property and cannot get into the backyard, so it leaves and comes back or skips the visit. On a ride-along with the first account, the founder watches a worker in a green T-shirt stop at a tall closed wooden gate, put a hand on his hip and look along its black metal straps, because the backyard he came to mow is locked. The founder then fills in one copy for that company and one for a solo operator with the same problem.
| Field | Account A: three crews | Account B: solo owner |
|---|---|---|
| Last occurrence | Last Tuesday, in the crew log | Yesterday, in the owner's route notes |
| Count in the last 13 weeks | 26 blocked visits, seen | 39 blocked visits, seen |
| Yearly count, assuming a 30-week season | 60 | 90 |
| Money out per occurrence | $12 of fuel for the return trip | $5 of fuel |
| Paid hours per occurrence | 2 crew hours at an assumed $30, or $60 | None; the owner is on the route anyway |
| Revenue lost per occurrence | $18 on average, because about one visit in four at $72 gets skipped | None; the owner returns the same day |
| Hours that do not count | None | About 20 minutes each, or 30 hours a year |
| Cost per occurrence | $90 | $5 |
| Yearly cost | $5,400, about five times the price, with payroll seen | $450, below the price |
| Who carries the cost | The owner, who named it unprompted | The owner |
| Step requested | $250 for a 60-day manual pilot, due in 2 weeks | $250 for a 60-day manual pilot, due in 2 weeks |
| Result | Paid inside the 2 weeks, tagged done | 'Send a link when it is ready', tagged said |
| Ratings | Frequency Strong, Cost Strong, Budget Strong | Frequency Strong, Cost Missing, Budget Missing |
| Reading | Looks paid for this account | Frequent inconvenience |
Account B has the higher count and the lower cost. Counted alone, frequency would put the solo owner ahead, which is why the blocks stay separate. The founder keeps the assumptions next to the result: that a 30-week season fits both accounts, that $30 an hour is a fair crew cost, that the 2 crew hours would really go to other paid work, and that a $250 pilot says something about paying $1,068 a year. Two copies are no verdict on the segment, so the next step is more copies from companies with crews.
How to use the worksheet without treating assumptions as facts
- Tag before you rate. Put the evidence tag on each entry first. A block resting on said or assumed entries cannot rate Strong, whatever the figures show.
- Change a tag only on new evidence. A said count becomes seen when someone shows the record, not when it starts to feel right.
- Keep an assumptions line. At the bottom of each copy, list every assumed figure and how to replace it: whom to ask and which record to see.
- Show the budget owner the yearly cost. Ask where it is wrong. A correction from the person who carries the cost is worth more than your estimate.
- Do not average the copies. Count how many accounts reached each reading, because an average hides the split between accounts.
- Keep blanks and refusals. An unknown field or a refused request is a result.
- Leave the margin alone once answers come in. If the results suggest a different margin, start a new set of copies under it.
The scorecard, its ratings and its readings are an editorial framework, not a measured result or a demand estimate. With a handful of accounts, a reading is a judgment about what to test next. The sheet suits business buyers with an identifiable budget owner better than consumer products, where purchase and usage data say more than interviews.
Related guides and next step
- The wider build, narrow or stop decision: Validate a Startup Idea Before Building
- Comparing several candidate problems: Is Your Startup Solving a Problem People Will Pay to Fix?
- Running the test across a dozen accounts: How to Test a Customer Problem Before Building a Product
- Recording each conversation: Customer Interview Notes Template for Founders
Daniel's go-to-market page says the first session is free and takes 30 minutes. Book a startup mentoring session and bring your completed copies to review your problem validation decision with your actual evidence and constraints.
Frequently asked questions
What should a problem severity scorecard include?
A header with the problem statement, segment, intended yearly price and required margin, then three blocks per account: frequency from records, the yearly cost of the current workaround, and the budget owner's commitment. Each entry carries an evidence tag of said, seen, done or assumed, and each block gets a rating of Strong, Partial or Missing.
What evidence should a founder collect for problem validation?
The date of the last occurrence and a count from a record; an invoice, payroll line or credit for the largest cost item; who carries that cost; and the step the budget owner completed, with its date. Keep refusals and unknown fields in the record, and mark anything unverified as assumed.
What are common mistakes in problem validation?
Treating a high count as evidence of a paid problem, counting hours from someone on shift regardless, using a founder estimate as a cost without tagging it, taking a promise or a free trial as commitment, averaging accounts, and moving the margin after the answers come in.
How does the scorecard separate a frequent inconvenience from a paid problem?
A frequent inconvenience rates Strong on frequency and Missing on cost and budget: it happens often, costs less per year than the intended price, and nobody gives anything up to test a fix. A paid problem rates Strong on cost and budget, with the largest cost item seen in a record and the budget owner completing a paid or dated step.