Do You Have Founder Market Fit or Just Industry Experience?
Industry experience becomes founder market fit only when it gives you something specific for the buyer you plan to sell to: people in that buyer role who will take your call, insight into how they decide, credibility they recognize and the ability to deliver. This applies to founders choosing a first market before committing time or capital. Inventory each advantage against that one buyer, test the weakest one first, and treat a gap in buyer access as the main constraint.
The choice and its business consequences
Years inside an industry feel like an advantage, and often they are. The question here is narrower: does your experience give you an advantage with the specific buyer you plan to sell to first, or only familiarity with the industry around that buyer? The answer changes what you do next. If the advantage is real, you can learn and sell faster than an outsider with that buyer. If it is familiarity only, you either choose a buyer where your experience does count or spend the first weeks closing the gap before building anything.
This guide is for founders at the idea or validation stage who are weighing an idea in an industry they know, and it looks at the founder side of that decision. Whether the idea itself deserves building is covered in Validate a Startup Idea Before Building and choosing between segments in How to Choose Your First Ideal Customer Profile as a separate step.
The independent evidence supports taking experience seriously. Azoulay, Jones, Kim and Miranda, in a working paper hosted by the US Census Bureau and dated March 23, 2018, link about 2.5 million founders to their prior employment histories. Their abstract says that 'prior experience in the specific industry predicts much greater rates of entrepreneurial success'. For the 1 in 1,000 highest-growth firms, they report that founders with three or more years of experience in the start-up's broad industry sector, at the 2-digit NAICS level, reached that outcome at twice the rate of founders with no experience in that sector, and that success rates rise as the experience matches the start-up's sector more closely.
Two limits matter for an individual decision. The figures are averages across millions of founders: they show which founders tended to reach high growth, not what experience will do for one person. And even for founders with at least three years in the start-up's narrowest industry category, the paper's rate of reaching the top 1 in 1,000 is 0.26 percent, against 0.11 percent for founders with no experience in the broad sector. The authors read the result as consistent with the importance of 'market knowledge', which they say 'can include both industry-specific human capital and social capital'. Founder market fit, as this page uses the term, asks whether your share of that knowledge and those relationships points at the buyer you have chosen.
Buyer access
In this inventory, buyer access is the deciding item. It asks whether people in the exact role that approves the purchase will talk to you soon, because of who you are. Knowing many people in an industry is a different thing. Years in a job tend to build relationships with colleagues, suppliers and peers in your own role, while the buyer of a new product often sits in another role or another type of company.
The US Small Business Administration's market research guidance says that 'market research helps you find customers for your business' and that asking consumers yourself 'can give you a nuanced understanding of your specific target audience', while warning that 'direct research can be time consuming and expensive'. Real access lowers that cost for a founder. Daniel's go-to-market page says, in a passage headed 'Where founders get go-to-market wrong': 'Selling to a market instead of a segment.' Access to an industry is access to a market. The test has to be run on a segment.
Test access directly. Write down the buyer role, list the named people in that role you could contact without a broker or a cold message, and ask each for a short conversation about how they handle the problem today. Count who agrees, not who is friendly. A low count does not end the idea. It means access is a gap to close, not an advantage to claim.
Category insight
Category insight is knowledge of how the buyer experiences the problem and how purchases in the category get decided: who signs, which budget pays, what the buyer uses today and what would make them switch. Industry experience can give deep insight into the operation and shallow insight into the purchase. A former operator knows what breaks. That is not the same as knowing why the person who pays has not fixed it.
A useful check is a prediction test. Before the next buyer conversations, write down the problems, current workaround and approval path you expect the buyer to describe. Afterwards, compare the written predictions with what buyers said. Insight is an advantage when most predictions hold. When they miss, your experience comes from a neighboring seat, and the conversations are teaching you the category the way they would teach an outsider.
Credibility and execution advantages
Credibility is whether this buyer gives you more trust, time or patience because of your background. It shows in behavior: a buyer who forwards your note to a colleague, agrees to a pilot sooner or accepts a rough first version. It is specific to the buyer. A reputation among peers in your former role can mean little to a buyer who sees you as a supplier or as the person from the other side of the table.
Execution is whether you can deliver what the buyer needs, including selling it. Operating experience can cover delivery without covering the selling motion of a new company. Daniel's go-to-market page says, in the same passage: 'Hiring salespeople before the founder has personally closed a deal.' The execution test is whether you can run the first sales with this buyer yourself, not whether you can run the operation you came from.
His page also says he built VisaNow.AI out of his own immigration ordeal and sold it 14 months later. That is a case of a founder starting from a problem lived firsthand. The page does not break the case down by advantage, so read it as his own account, not as a test of this framework.
The founder advantage inventory
Copy this inventory into a document and fill in one copy per candidate buyer, not per industry. Score each row from zero to two: zero with no evidence, one with partial evidence, two when the evidence that counts has been observed recently with this buyer.
| Advantage | Question for this buyer | Evidence that counts | Does not count | Fastest test |
|---|---|---|---|---|
| Buyer access | Will people in the approving role talk to you because of who you are? | Named people in that role who agreed to a conversation | The size of your industry network, or people in your former role | Ask a list of named buyers for a short conversation and count acceptances |
| Category insight | Do you know how this buyer decides and pays? | Written predictions that buyer conversations then confirmed | Knowing the operation well, or opinions about the industry | Write predictions before the calls and compare them afterwards |
| Credibility | Does your background earn this buyer's trust or time? | Forwarded notes, referrals and faster agreement to a pilot | Job titles, former employers and praise from peers | Note who forwards or refers you after a first conversation |
| Execution | Can you deliver and sell to this buyer now? | Work delivered for this buyer type, or a first sale you closed yourself | Running a similar operation for an employer | Offer a small paid version and try to close it yourself |
Read the scores before deciding anything:
- Buyer access at zero. Treat the idea as unproven for this buyer, whatever the other scores say. Close the access gap first or score a different buyer.
- Access strong, insight weak. You can learn fast here. Use the access to run the prediction test before building.
- Insight strong, access weak. Check for this pattern first if your experience comes from operating roles. Look for a buyer closer to your own former role, or a co-founder or early hire who has the access.
- All four strong. That is founder market fit for this buyer. It still does not show demand, so run the problem and commitment tests in the guides linked above.
A worked decision with explicit assumptions
The following is a hypothetical example with invented details. It illustrates the inventory and does not describe a real person, company or measured result, and it is not guidance on beekeeping or farming.
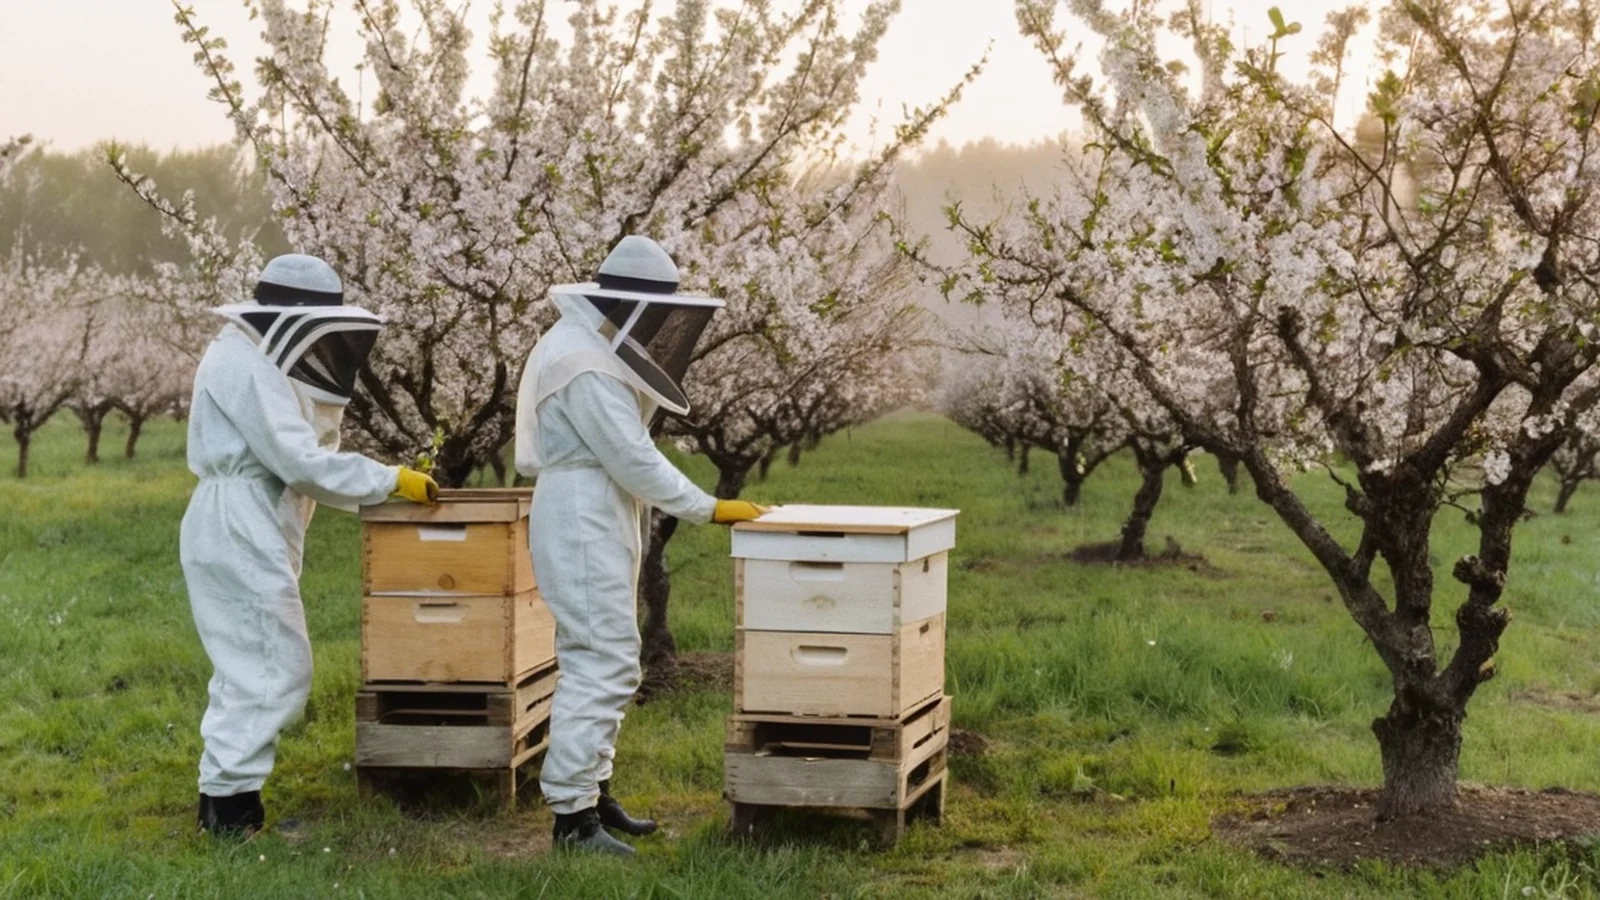
A founder has spent 11 seasons as a commercial beekeeper, moving hives into almond orchards each spring for pollination. The idea is a booking service that matches orchard growers with beekeepers and records where each hive was placed. At first light on the last move of the season, the founder and a helper rest their hands on the final two hives, set on pallets under the blossoming trees. The grower who owns the orchard is not there. In 11 seasons the founder has spoken with him twice, both times through the pollination broker.
Two first buyers are possible: growers, who would pay per booking, or other beekeepers, who would pay a monthly fee to manage their own bookings. The founder contacts 10 of each and scores the inventory for both:
| Advantage | Growers | Beekeepers |
|---|---|---|
| Buyer access | 0: 3 of 10 agree to a call, all arranged by the broker | 2: 9 of 10 agree within a week |
| Category insight | 1: 1 of 3 written predictions about growers holds | 2: 3 of 3 predictions hold |
| Credibility | 0: no grower forwards the founder's note | 2: 4 beekeepers refer another beekeeper |
| Execution | 1: can deliver, has not sold to a grower | 1: can deliver, has not sold software |
| Total | 2 of 8 | 7 of 8 |
The reading rules decide it. Grower access scores zero: the 3 calls came through the broker, so they show the broker's access, not the founder's. The beekeeper side scores 7 of 8, so the founder starts there, with a hive placement record that beekeepers pay for monthly, offered first to the 9 who agreed to a call. Growers stay in the plan as a later buyer with a written test: 5 grower conversations arranged without the broker within 6 weeks, or the grower side of the idea is dropped.
The assumptions stay written down: that 10 contacts per side are enough to compare access, that beekeepers will pay a monthly fee rather than only use a free tool, that the 3 predictions cover what matters to growers, and that a record kept by beekeepers will later be useful to growers. None of this is measured yet. The first paid month from beekeepers, closed by the founder, is the next test, and it is also the execution test.
Common mistakes and limits
- Scoring the industry instead of the buyer. The same founder can have strong fit with one buyer and none with the buyer next to it.
- Counting the network, not the acceptances. Contacts who are friendly but will not take a call about the problem are not access.
- Borrowed access. Conversations arranged by a broker, investor or former employer show their access, not yours, unless they keep arranging them.
- Treating operating knowledge as purchase knowledge. Knowing what breaks is different from knowing who pays to fix it.
- Reading fit as demand. A full inventory says you are well placed to find out. It does not say the buyer will pay.
The inventory has limits. Its rows, scores and reading rules are an editorial framework, not a validated instrument. The research cited here describes averages across a large population of founders and cannot score one founder's fit with one buyer.
Related guides and next step
- Deciding whether the idea deserves building: Validate a Startup Idea Before Building
- Choosing between candidate segments: How to Choose Your First Ideal Customer Profile
- Turning relationships into useful next steps: Founder Networking Worksheet: Relationships and Useful Next Steps
Daniel's go-to-market page says the first session is free and takes 30 minutes. Book a startup mentoring session to review your founder market fit decision with your actual evidence and constraints, and bring a filled inventory for each buyer you are considering.
Frequently asked questions
Do You Have Founder Market Fit or Just Industry Experience?
You have founder market fit when your experience gives you access to the buyer you plan to sell to, insight into how that buyer decides, credibility that buyer recognizes and the ability to deliver and sell to them. If your advantages point at the industry in general, or at people in your former role, you have industry experience. Score each advantage against one named buyer to tell the difference.
What evidence should a founder collect for founder market fit?
Named people in the buyer role who agreed to a conversation, written predictions about the buyer's problems and approval path compared with what buyers then said, referrals or forwarded notes after first conversations, and any work delivered or sale closed with that buyer type. Collect it per candidate buyer, with dates.
What are common mistakes in founder market fit?
Scoring the industry instead of a specific buyer, counting the size of a network instead of accepted conversations, treating conversations arranged by a broker or investor as the founder's own access, confusing knowledge of the operation with knowledge of the purchase and treating a strong inventory as evidence of demand.
Does industry experience improve the odds of startup success?
On average, research using US Census Bureau data reports that founders with prior work experience in a start-up's industry reach high-growth outcomes at higher rates, and that closer industry matches show higher rates. Those are averages across many founders. They do not show whether one founder's experience transfers to one buyer, which is what the inventory tests.